USAA Mobile

Screenshots
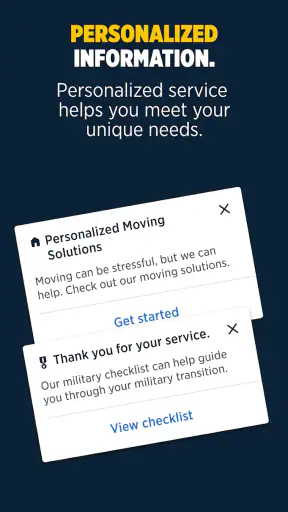
Details
- Rating
- 66.11K reviews
- Version
- 11.15.2
- Developer
- USAA
Analysis by Norviv
Managing money from a phone only works when convenience does not come at the expense of confidence. I spent time with USAA Mobile as a finance app for bringing insurance, banking, and investment accounts into one place, and my overall impression is that it is most useful for people who already have a relationship with USAA. It feels less like a general-purpose money organizer and more like a central control panel for a specific financial household.
The app is free, developed by USAA, and intended for Everyone. Its current Android version is 11.15.2 and requires Android 12 or later. Those details matter more than they may seem: someone with an older phone cannot simply install it, while a recent Android user should have a straightforward starting point. On the store, it has a 4.7 average from roughly 497 thousand ratings, with more than 10 million installs. That level of adoption suggests a well-established mobile service, although popularity alone is not a substitute for checking whether its account controls suit you.
What I trusted, and what I checked first
I start with the point where trust becomes practical: whether I can tell what I am viewing and keep a routine check from turning into a rushed decision. I look at how the app fits into a USAA account relationship, then consider the small checks that help me use a financial hub deliberately. That foundation makes it easier to build repeatable habits without treating convenience as a substitute for care.
A focused home for a USAA relationship
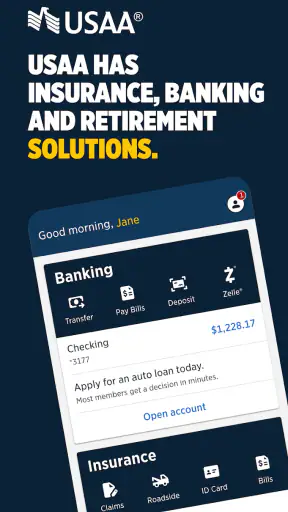
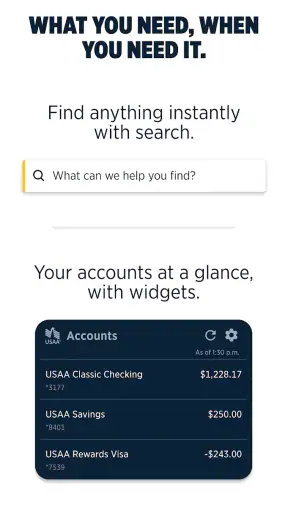
My first useful observation was that the app makes sense when several parts of your financial life already sit with USAA. Instead of switching among separate insurance, banking, and investment experiences, you can approach them from the same mobile environment. That can reduce the small but irritating work of remembering which service to open when you are checking a balance, reviewing coverage, or looking at an investment account.
That focus is also the app's main boundary. If your accounts are spread across several unrelated providers, USAA Mobile will not automatically become a complete picture of your finances. It is not the obvious replacement for a budgeting app that is designed around multiple institutions, nor is it the best reason to move every account you own. I would treat it as a companion to a USAA relationship, not as a universal financial dashboard.
Trust begins with knowing what you are opening. The store summary describes secure access to USAA insurance, banking, and investment accounts, so I approached it as an access and management tool rather than as a financial adviser. That distinction is important. An app can make account information easier to reach without making decisions for you, and I prefer that separation when money is involved.
Why the developer and account context matter
USAA is the developer behind the app, which gives the experience a clear connection to the accounts it presents. For me, that is more reassuring than a third-party app attempting to sit between several financial providers, because the purpose is easier to understand: access the services associated with the USAA relationship through a mobile device.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Still, I would not let a familiar name remove basic caution. A financial app deserves the same care as a physical wallet. I would install it only through the official app marketplace, keep the phone's operating system current, and avoid signing in while connected to an unfamiliar network. Those are habits I use with every money app, but they are particularly sensible here because the application can bring together banking, insurance, and investment information.
The age rating of Everyone tells you the app is not presented as mature-content software; it does not mean every financial decision inside it is suitable for every person. A teenager, a new account holder, or a family member using a shared device may still need guidance about sign-in privacy, notifications, and what account information is visible after access is granted.
Controls I would verify before relying on it
Before using any finance app as my daily access point, I look for practical control rather than impressive wording. Can I sign out clearly? Can I recognize which account or service I am viewing? Can I review an action before confirming it? Can I tell whether I am looking at insurance, banking, or investments? These questions are more useful to me than a vague promise of convenience.
USAA Mobile's value comes from putting those service areas close together, but that also creates a responsibility for the user: slow down before acting. A quick glance at a balance is different from changing an insurance-related detail, moving money, or reviewing an investment position. I would never treat the app's speed as a reason to rush through a consequential screen.
The most important control is deliberate confirmation before a financial action. I recommend reading the destination, amount, account type, and final review screen every time rather than relying on muscle memory. This is a small habit, but it protects against the common mobile mistake of tapping through a familiar-looking workflow too quickly.
Notifications, device access, and personal boundaries
Notifications are one of the first areas where I would make a personal choice. They can be useful for keeping track of account activity or reminders, but a lock-screen message can also reveal more than you want someone nearby to see. I would review notification behavior after installation and decide whether previews belong on the lock screen, especially if the phone is shared, left on a desk, or used around family members.
I also prefer a dedicated device profile for financial access. A screen lock, current system updates, and the absence of unnecessary people using the phone make a bigger difference to my comfort than any single app setting. If another person needs occasional access to a household account, I would rather use an intentional, supervised process than leave the phone unlocked with the app open.
When an app requests access to a device feature, I look at the reason and the choice presented to me instead of approving everything automatically. I would grant only what is needed for the task I intend to perform, revisit permissions later, and remove access that no longer makes sense. I am not treating a permission prompt as proof of danger or safety; I am treating it as a moment where the user should remain in control.
Data-sensitive moments deserve extra attention
The most sensitive moments are not limited to signing in. Opening a bank balance in a public place, reviewing investment information while screen sharing, checking insurance details on a borrowed device, or leaving a confirmation screen visible can expose private information even when the app itself is working normally.
My practical rule is to separate browsing from action. I might check a balance quickly, but I would wait until I have privacy before changing account information or starting a transaction. If I am helping a relative, I would let them hold the phone and enter their own credentials rather than asking them to dictate sensitive details to me.
Insurance information can also be more revealing than a simple account total. Coverage details, household information, and documents may be useful in an emergency, but they should not be casually displayed. I would avoid taking screenshots unless there is a clear reason, and I would check where those images are stored before sharing them.
Investment accounts create a different kind of sensitivity. A mobile view can make market information feel immediate, which may encourage impulsive checking or action. I find it healthier to use the app for reviewing information and completing a considered task, not for turning every price movement into a prompt to react. The convenience is real, but convenience should not become pressure.
How I would use it in an ordinary week
Imagine I am preparing for a weekend trip. I could open the app to review a banking account, check an insurance detail, and look at an investment account without searching through several unrelated apps. That is the kind of everyday consolidation where USAA Mobile earns its place. I would do the quick review at home, confirm that I am in the intended account area, and close the app when finished rather than leaving it available in the app switcher.
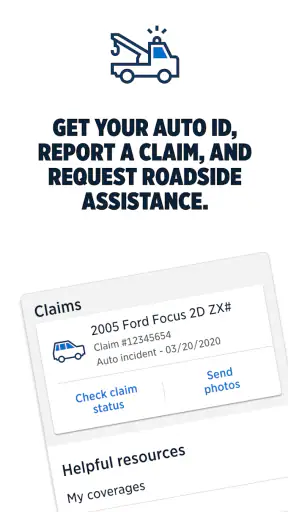
Another realistic situation is a car-related question after a minor incident. I might need to locate insurance information while feeling distracted or stressed. In that moment, the advantage is not just fewer taps; it is having a familiar starting point. I would still verify the information carefully and avoid making a rushed change simply because I am already inside the app.
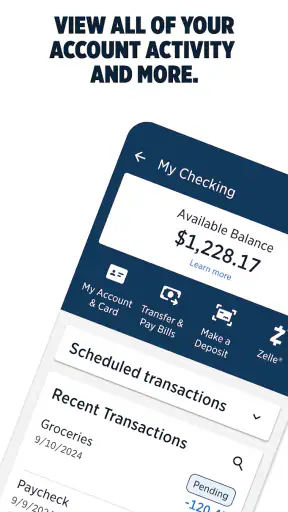
For routine banking, I would use it as a check-in tool: confirm the account I meant to view, inspect recent activity, and then leave. For investments, I would use a slower approach, reviewing the relevant information when I have time to think. The same app can support both tasks, but the right behavior is different for each one.
Where it compares well with usual alternatives
Compared with separate provider apps, USAA Mobile has an obvious advantage for a USAA customer: fewer places to remember and a more unified path to related services. Compared with a general budgeting app, its strength is direct access to the underlying USAA relationship rather than broad household categorization across many institutions.
A budgeting app may be better if your priority is spending analysis across several banks, cards, and financial services. A dedicated investment platform may be preferable if you want a specialized research environment. A standalone insurance app from another provider may be the more natural choice if your coverage is not with USAA. I would choose according to the job, not according to which app has the most features on paper.
The trade-off is concentration. Having several financial areas near each other is convenient, but it also means the app becomes more important to your routine. If access is temporarily inconvenient, you may feel that impact across more than one part of your financial life. I would keep essential account information available through appropriate backup channels and know how to contact the relevant service without depending entirely on one screen.
Small habits that make the experience safer
Use a strong device lock and do not leave the app open when someone else can pick up the phone.
Review notification previews so account-related information is not unnecessarily visible from the lock screen.
Before confirming an action, pause and check the account area, destination, and amount or detail being changed.
Separate quick balance checks from decisions involving insurance changes or investments; the latter deserve privacy and time.
Keep the app and Android updated, and remove access from devices you no longer use.
These are not glamorous tips, but they are the difference between merely installing a finance app and using one responsibly. They also preserve user agency. The app can organize access, but I remain responsible for deciding when to act, what to share, and whether a request makes sense.
Who should use it, and who should skip it?
I would recommend USAA Mobile to an existing USAA customer who wants one mobile starting point for insurance, banking, and investment accounts. It is especially appealing if you regularly move between those areas and dislike keeping several service-specific apps in your routine. The free price also makes trying it straightforward, provided your device meets the operating-system requirement.
I would be more cautious about recommending it to someone who wants a complete cross-provider budget, detailed spending analytics, or a specialized investing workspace. Those users may be happier with tools built around those particular goals. I would also skip it as a primary choice if I had no USAA relationship; the app's usefulness is tied closely to the services it is meant to access.
Families should discuss access before sharing a device. A parent may want a convenient way to supervise household finances, while another adult may reasonably want separate credentials and privacy. The app cannot replace that conversation. I would set expectations about who uses the phone, which notifications appear, and whether anyone else is allowed to view account screens.
My cautious verdict
After using USAA Mobile as a finance hub, I see its strongest quality in its focused purpose. It brings USAA insurance, banking, and investment access into a single mobile experience, which can make routine financial checks less fragmented. Its large user base and 4.7 average rating are encouraging signs of familiarity, but I still judge it by the controls and habits that matter during real use.
I like it best when the user treats it as a secure doorway, not as a background utility. Open it intentionally, check the service area, protect notifications, and slow down for anything consequential. That approach makes the convenience work without handing over more attention or visibility than necessary.
My final recommendation is therefore specific: choose it if you already use USAA and want consolidated mobile access; look elsewhere if your main need is provider-neutral budgeting or highly specialized investing. USAA Mobile is most convincing when convenience stays under the user's control. Used that way, it is a practical free app for everyday account access, with enough flexibility to support routine checks while still rewarding careful, privacy-minded behavior.
Frequently Asked Questions
01What is USAA Mobile, and who can use it?
USAA Mobile is the official banking and financial-services app for USAA members. It lets eligible users manage checking and savings accounts, credit cards, loans, insurance policies, investments, and other services from an Android or iOS device. Membership is generally limited to eligible military members, veterans, and qualifying family members, so you should confirm your eligibility before downloading and registering.
02What can I do with the USAA Mobile app?
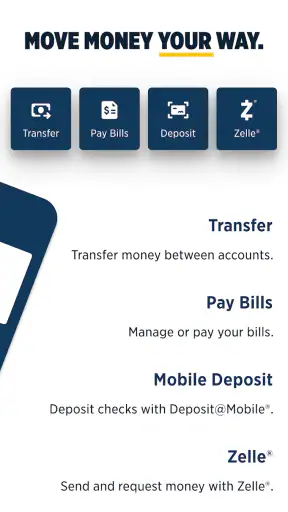
The app provides access to many everyday financial tasks in one place. Depending on your accounts and eligibility, you can review balances and transactions, transfer money, pay bills, deposit checks by taking photos, send payments, manage cards, request roadside assistance, view insurance information, and contact USAA support. Available features may differ by product, location, device, and account status.
03Is USAA Mobile safe for banking and insurance management?
USAA Mobile includes standard security protections such as encrypted connections, secure sign-in, device verification, alerts, and options such as biometric authentication when supported by your phone. Even so, no financial app is completely risk-free. Download it only from the official Google Play Store or Apple App Store, keep your operating system updated, avoid public Wi-Fi for sensitive tasks, and never share verification codes or passwords.
04Does USAA Mobile charge fees for using its features?
Downloading and using the USAA Mobile app is generally free, but the app does not automatically eliminate fees associated with specific financial products or transactions. Charges can depend on your account agreement, ATM usage, transfers, payment services, insurance products, or other activity. Review the applicable terms and fee disclosures in your account before completing a transaction, especially when using external banks or third-party services.
05What should I do if USAA Mobile is not working or I cannot sign in?
First, check your internet connection, update the app, restart your device, and confirm that your phone meets the current Android or iOS requirements. If the problem continues, avoid repeatedly entering incorrect credentials, since this may trigger additional security restrictions. Use the official USAA website or customer-service channels for assistance, and contact USAA promptly if you suspect unauthorized access or unusual account activity.


